


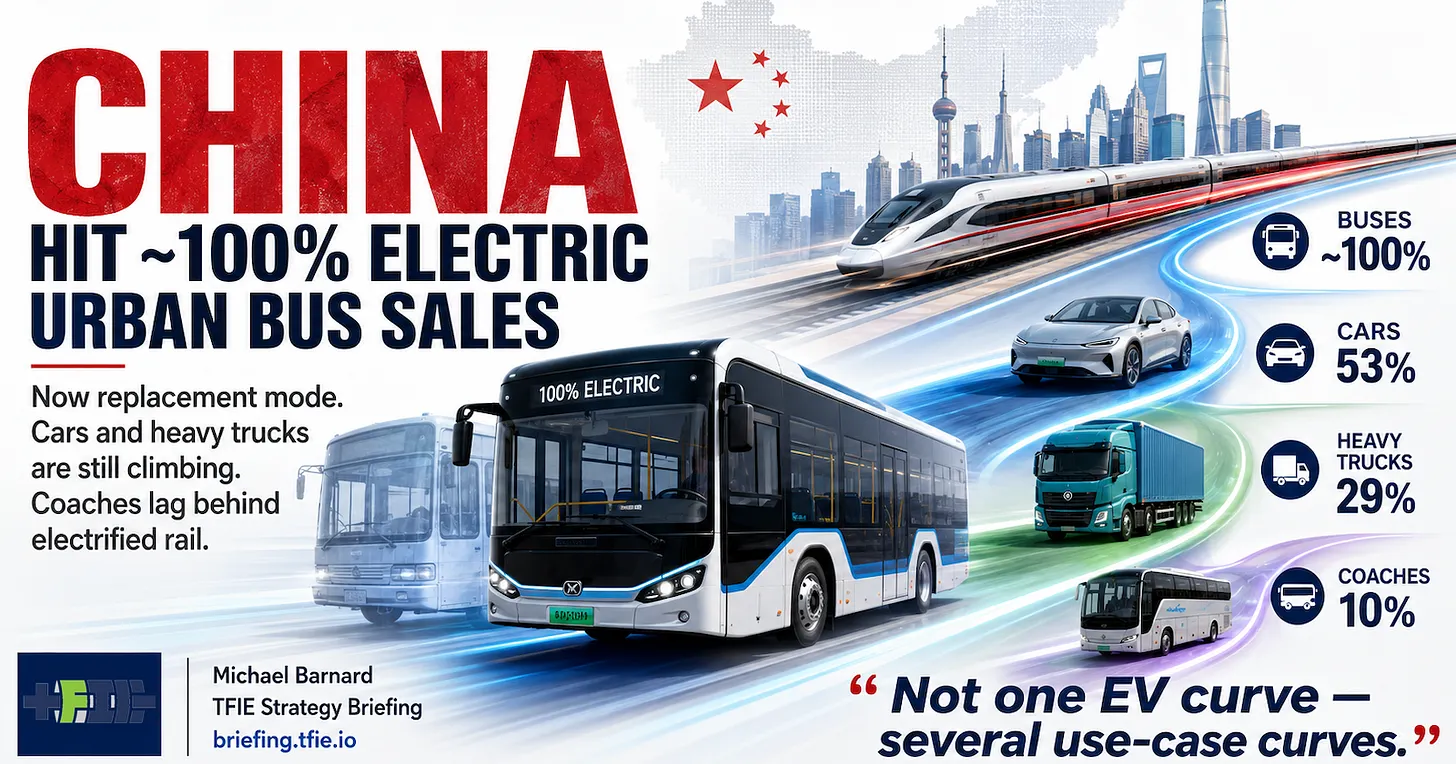
China has reached a stage of auto electrification that’s straightforward to overlook if the one quantity being watched is nationwide EV market share. New city buses are actually basically all electrical, and in lots of cities the procurement query is not whether or not to switch a diesel bus with a battery bus. It’s which new electrical bus ought to exchange the electrical bus purchased throughout China’s first main electrification wave.
That may be a extra necessary milestone than one other file yr of EV gross sales as a result of it reveals a transport phase finishing its first adoption cycle and getting into routine substitute. The Worldwide Power Company estimates that just about 70% of China’s greater than 680,000 electrical buses had been already deployed earlier than 2020, so a big half of the present market consists of older electrical fleets being renewed quite than diesel fleets being transformed for the primary time.
China’s 2025 equipment-renewal programme explicitly supported substitute of new-energy metropolis buses and even full traction-battery substitute, with the programme persevering with into 2026. Coverage remains to be concerned, however its job has modified. It’s supporting renewal inside a market the place electrical propulsion has already change into the conventional know-how.
That substitute cycle is the place to begin of my TFIE Technique Briefing evaluation of China’s electrical transport markets. Wanting throughout buses, vehicles, heavy vehicles and coaches reveals why “China’s EV adoption charge” is more and more the fallacious denominator.
Passenger vehicles are at a unique level. Electrical vehicles accounted for simply over half of Chinese language new-car gross sales in 2025, and consumers had practically 700 electrical fashions accessible by the tip of the yr. The IEA estimates that almost 70% of battery-electric vehicles offered in China had been cheaper than comparable standard vehicles even earlier than incentives, which suggests electrical propulsion is not a specialist various for Chinese language automobile consumers. It is likely one of the regular selections throughout a lot of the market.
Heavy vehicles are behind vehicles in absolute market share however are transferring a lot sooner. Electrical heavy vehicles reached about 29% of Chinese language gross sales in 2025, roughly twice their 2024 share. Their strongest markets are usually not random: ports, mines, metal crops and industrial logistics operations give vehicles comparatively predictable routes, excessive utilization and locations the place charging or battery swapping might be organized across the work.
That’s what makes business automobiles significantly fascinating. A non-public automobile might spend most of its life parked, so gas financial savings accumulate comparatively slowly. A tough-working truck can cowl sufficient kilometres that decrease power and upkeep prices have an effect on the enterprise case a lot sooner, particularly when infrastructure might be concentrated at depots or alongside mounted corridors.
Intercity coaches present why even that logic can not merely be prolonged to each transport class. Battery-electric coaches had been solely about 10% of Chinese language coach gross sales in 2025, regardless of gross sales rising strongly from the earlier yr. At first look that appears like a class lagging badly behind city buses. The distinction is just not merely that coaches want greater batteries. They compete with one other electrical know-how that China scaled a long time sooner than most international locations: rail.
China ended 2025 with greater than 50,000 kilometres of high-speed rail, whereas its railway system carried greater than 4.5 billion passenger journeys in the course of the yr. Excessive-speed rail reaches virtually each Chinese language metropolis with greater than half 1,000,000 city residents, and it supplies one- to two-hour journeys throughout many 500-kilometre metropolis clusters and roughly four-hour journeys throughout some 1,000-kilometre corridors.
A battery coach can exchange a diesel coach on routes the place street transport nonetheless is smart, nevertheless it doesn’t must seize each long-distance passenger journey that may in any other case have passed by bus. A few of that mobility has already moved to an electrified mode with higher efficiency on dense intercity corridors.
Because of this nationwide EV percentages can obscure greater than they make clear. Metropolis buses, passenger vehicles, heavy vehicles and coaches all have wheels and batteries, however their economics are very totally different. They function for various numbers of hours, return to totally different locations, carry totally different hundreds, use totally different infrastructure and face totally different alternate options.
A helpful forecast begins with the work being achieved quite than with a single adoption curve. Mounted-route city buses electrified early as a result of batteries matched the obligation cycle and public procurement might coordinate charging. Passenger vehicles adopted as battery prices fell, mannequin selection expanded and buy costs grew to become aggressive. Heavy vehicles are actually accelerating the place excessive utilization turns working financial savings into a powerful business incentive.
Coaches will electrify too, however their addressable market is formed by what rail has already captured. That isn’t a weak point in China’s transport electrification story. It’s proof that the target is mobility with much less fossil gas, not forcing each current automobile class to develop into an equally giant electrical market.
There’s additionally an information caveat value preserving. Chinese language sources have traditionally used overlapping classes similar to “new power bus,” and successive IEA editions have revised classifications as higher information grew to become accessible. The exact form of the early bus curve is much less sure than the big sample: city buses moved first and are actually saturated, vehicles are mainstream, heavy vehicles are climbing rapidly and coaches stay a lot much less electrified.
For policymakers exterior China, the implications are sensible. A rustic with a low nationwide EV share mustn’t assume each transport phase will crawl upward on the similar charge. Some classes can transfer in a short time as soon as automobiles, working economics and infrastructure align, whereas different classes might stay smaller as a result of one other mode does a part of the job higher.
That adjustments how public cash needs to be spent. Quite than subsidizing each electrical automobile class equally, governments can establish the makes use of the place electrification already matches the work, take away the infrastructure bottlenecks and permit these markets to maneuver first. Buses, depot-based fleets, high-utilization vehicles and different predictable business functions typically present clearer beginning factors than attempting to make a whole transport sector transfer collectively.
China’s expertise means that the mature endpoint won’t be one easy EV adoption curve. Will probably be a number of totally different transitions unfolding in response to the work every automobile performs and the transport techniques round it.
The complete TFIE Technique Briefing compares the gross sales trajectories for Chinese language city buses, passenger vehicles, heavy vehicles and coaches, together with why high-speed rail adjustments the coach denominator and why substitute quite than first adoption is now driving a lot of the urban-bus market.
