


Help CleanTechnica’s work via a Substack subscription, on Patreon, or on Stripe. Assist us produce all the high-quality, authentic content material we publish week after week regardless of the challenges of content-scraping AI, delinquent media, inflation, and different hurdles.
Petrol mannequin gross sales crash 44% in July!
Excessive fuel costs and a endless wave of latest BEVs has allowed July to succeed in document EV market share, with plugins reaching a document 65%!
Nevertheless, whereas document market share was achieved prior to now because of sturdy EV gross sales, this time, the document achievement is because of a major ICE (inner combustion engine) crash. The general market dropped 21% 12 months over 12 months (YoY), to round 1.5 million gross sales. ICE-powered fashions have been on the epicenter of this disruption, with pure petrol bearing the majority of the gross sales drop (-44% YoY). Slightly surprisingly, HEVs dropped by solely 4%, lower than plugin hybrids (PHEVs), which fell 21% in July, and prolonged vary fashions (EREVs), which have been down 17%.
Contemplating the doom and gloom described above, there was nonetheless purpose for hope. And what would possibly that be? Pure electrics. Regardless of having fewer incentives, BEVs have been up 6% YoY, to 647,000 gross sales. This meant that BEVs scored a document 44% BEV share in China!
Including PHEVs (21% share) to the tally meant that in July, a document 65% of all vehicles offered in China had a plug! Evaluating this consequence with the place we have been a 12 months in the past, it’s an 11% share enchancment. In July 2025, the plugin share was 54%…. If this pattern continues sooner or later, the Chinese language market shall be totally electrified earlier than 2030, and 100% BEV earlier than 2035!
This nice consequence pulled the 2026 share up, to 56%, already 2% above the complete 12 months results of 2025. BEVs on their very own have been as much as 37% (versus 33% in 2025).
At this tempo, I anticipate the ultimate quantity for 2026 EV share in China to be round 60%, with BEVs alone north of the 40% mark. And when the most important international automotive market will get this electrified … then the ICE business is in deep trouble.
(Which implies that investing cash in R&D for ICE expertise at the moment is throwing cash out the window, as there received’t be sufficient time to pay again the funding prices.)
One other fascinating statistic is that the breakdown between pure electrics and plugin hybrids is shifting, to the revenue of BEVs. Originally of the 12 months, PHEVs have been making the most of the incentive-derived BEV drop, however pure electrics are returning with a vengeance. July confirmed a 68% vs. 32% breakdown, to the advantage of BEVs, with the 2026 common at 66%/34%.
Traditionally, that is the very best BEV share since 2023, and a step within the return to the 80% vs 20% breakdown of the primary years within the Chinese language EV market. With PHEVs dropping incentives on the finish of this 12 months, 2027 may very well be the primary 12 months since 2022 to see that form of gross sales breakdown.
One other seismic change occurring within the Chinese language automotive business is the rising significance of exports for native OEMs. In July alone, over half 1,000,000 items have been exported, a 148% soar YoY, with the EV share of these exports following intently the home market — 59% EV share in July vs 45% in July ’25.
As a consequence of these vital month-to-month EV exports from Chinese language automakers, legacy OEMs should not solely struggling within the Chinese language market, which is the most important on the planet, but in addition being squeezed elsewhere, so it’s nothing greater than a pipe dream to suppose that they will maintain the Chinese language tsunami by preserving their ICE fashions in markets outdoors China.
As a secondary impact of this export push is that as a result of Chinese language exports are additionally closely electrified, at round half of the volumes, export markets are additionally being electrified as Chinese language OEMs progressively acquire share.
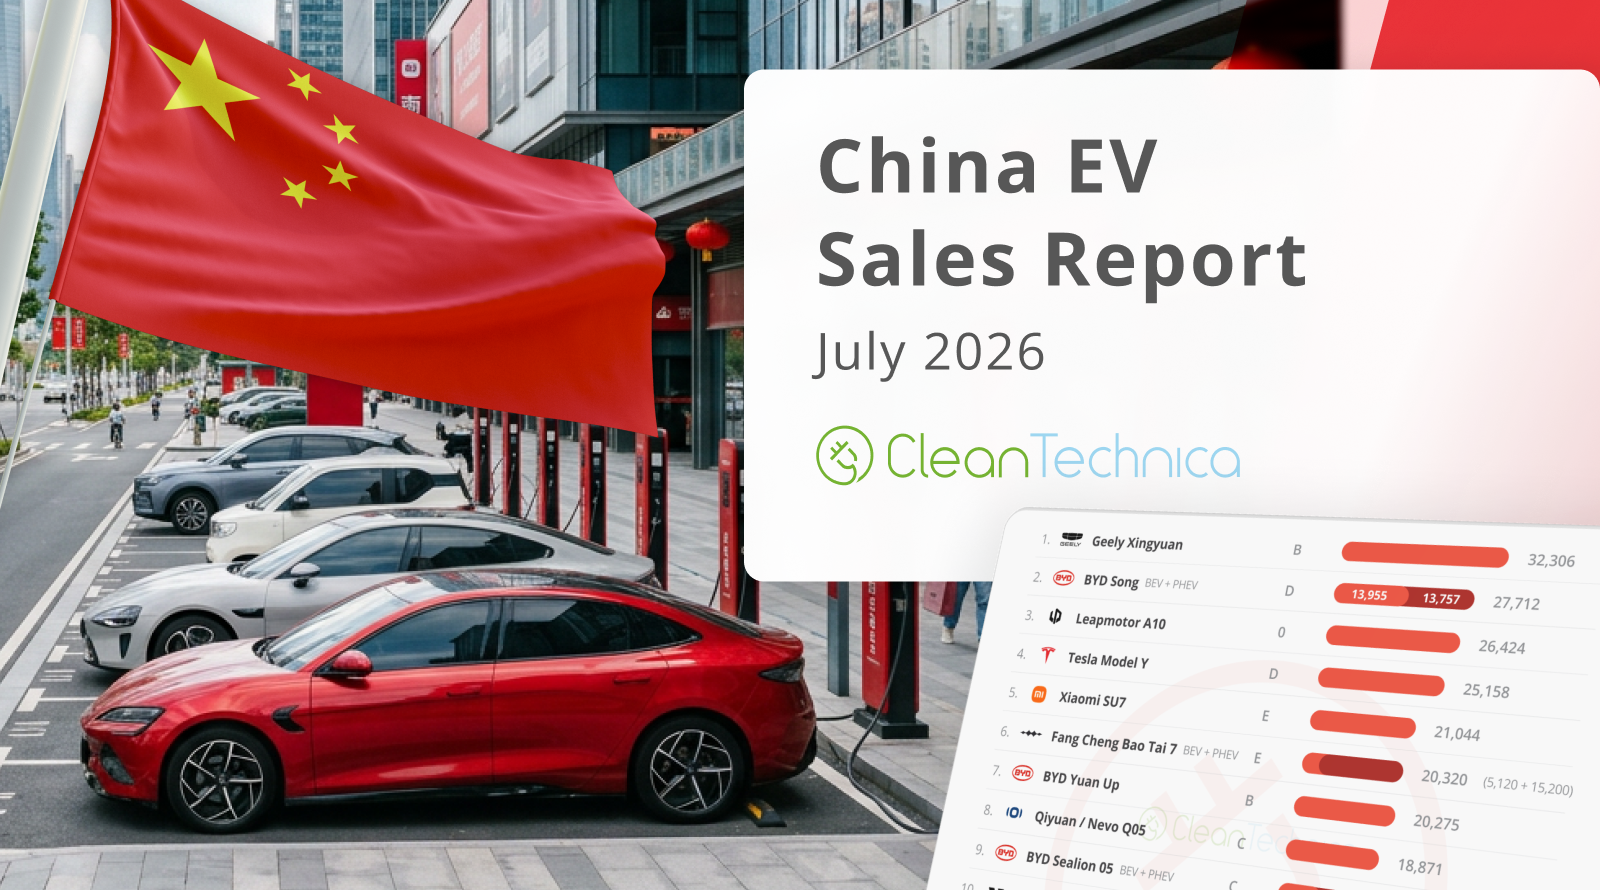
The ICE meltdown can also be seen within the general rating. Within the first months of the 12 months, ICE fashions have been populating the highest positions, however following what occurred in Might and June, we now have one other all-EV high 10 in July within the general market, seven of them being pure electrical fashions!
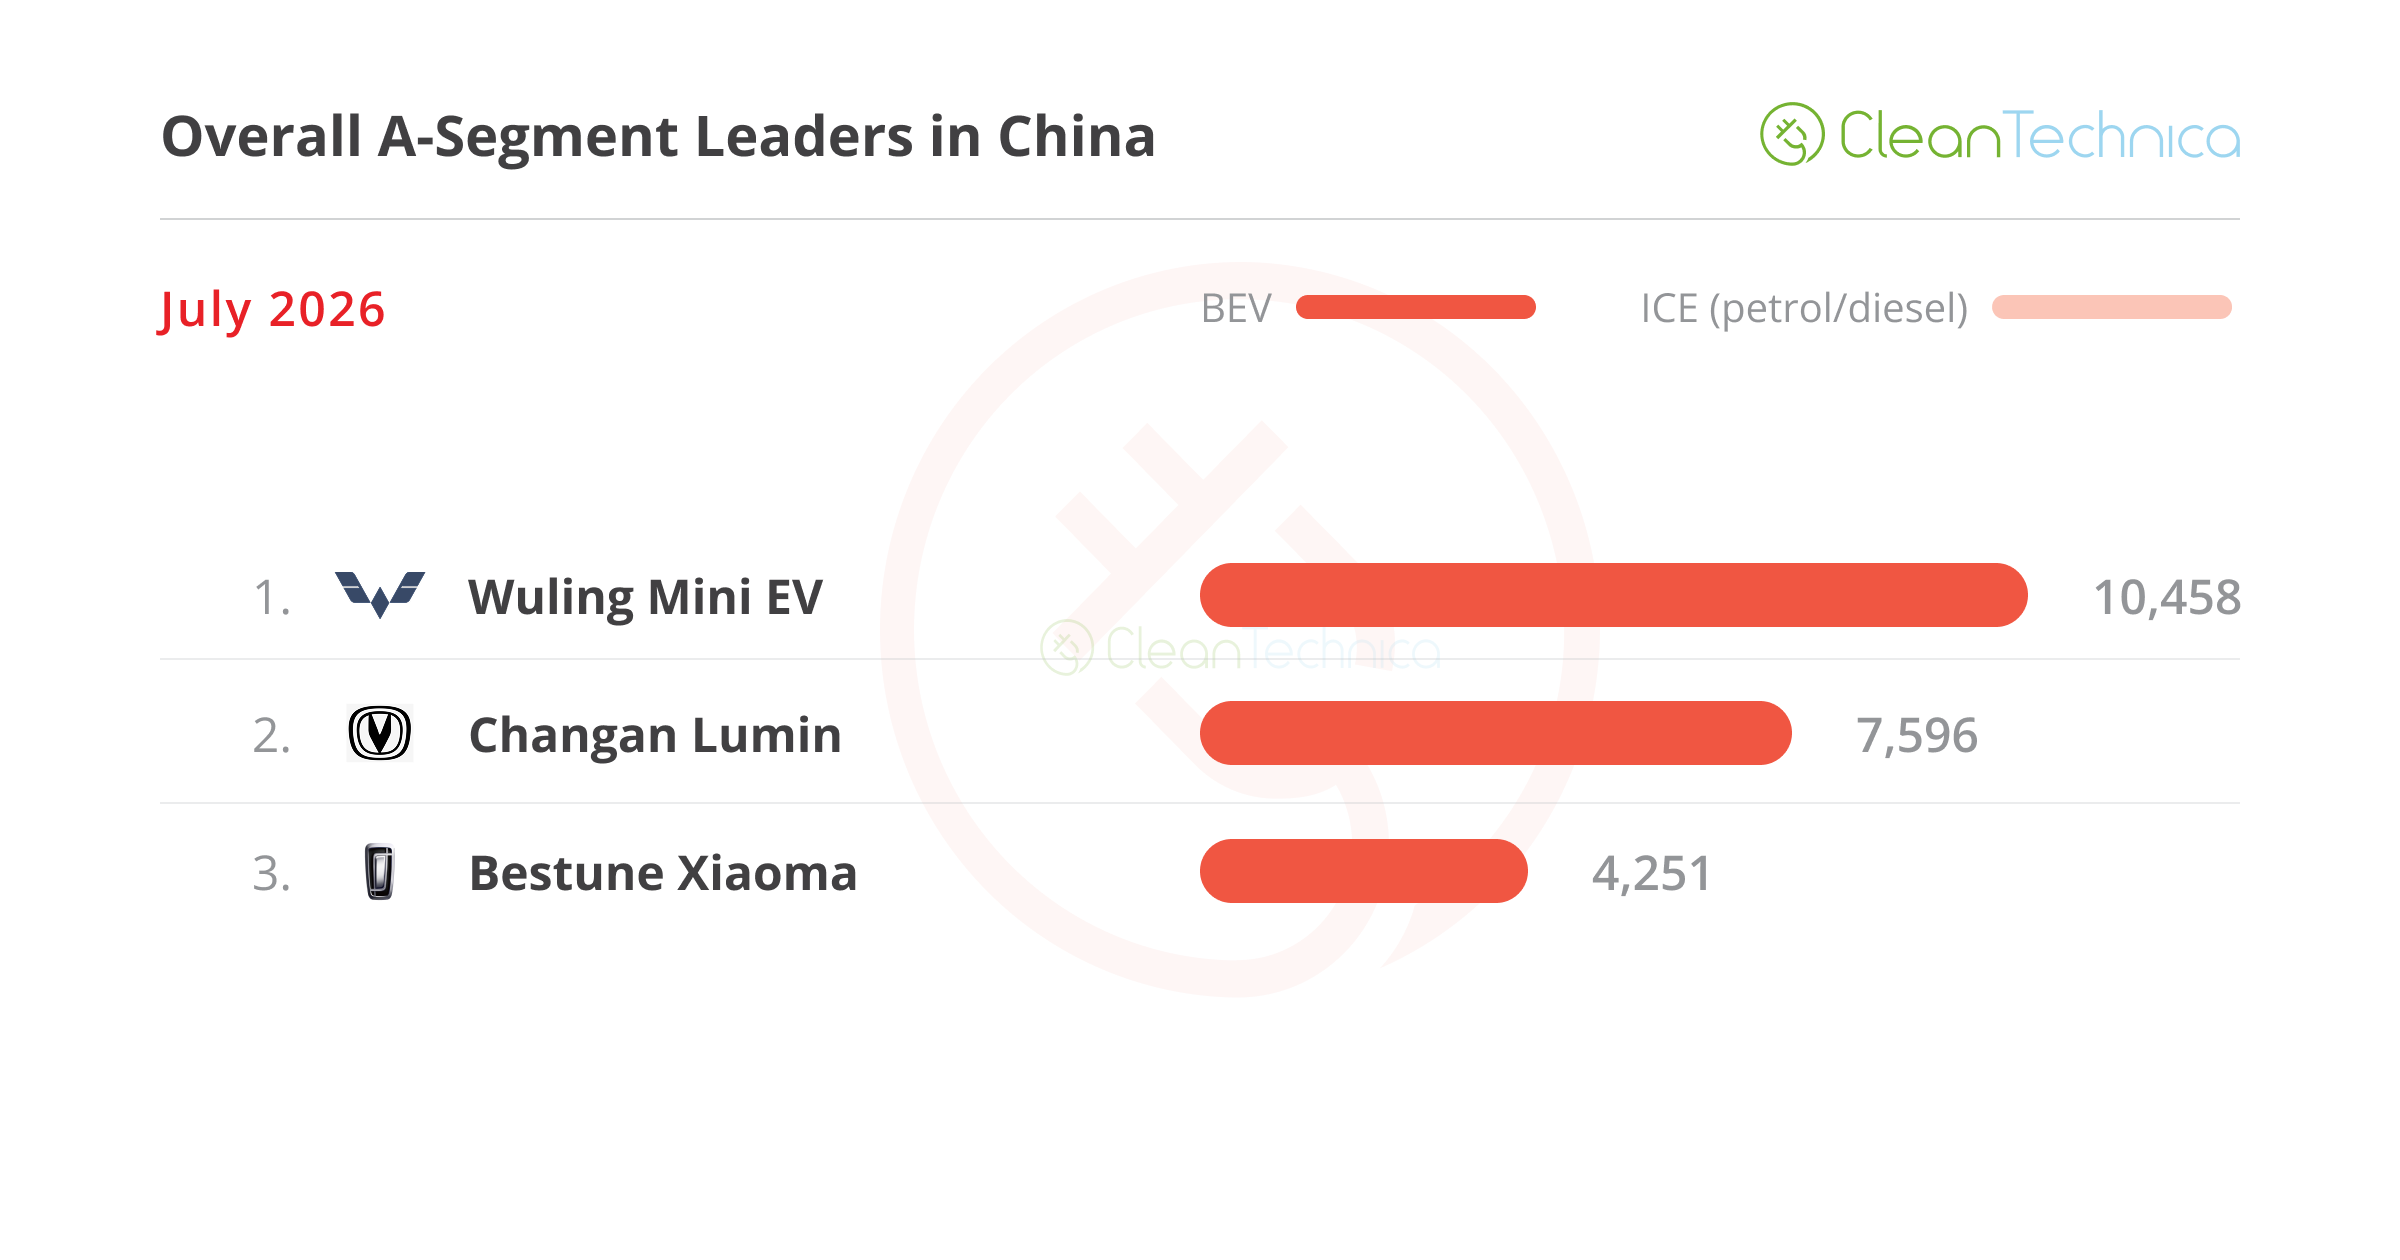
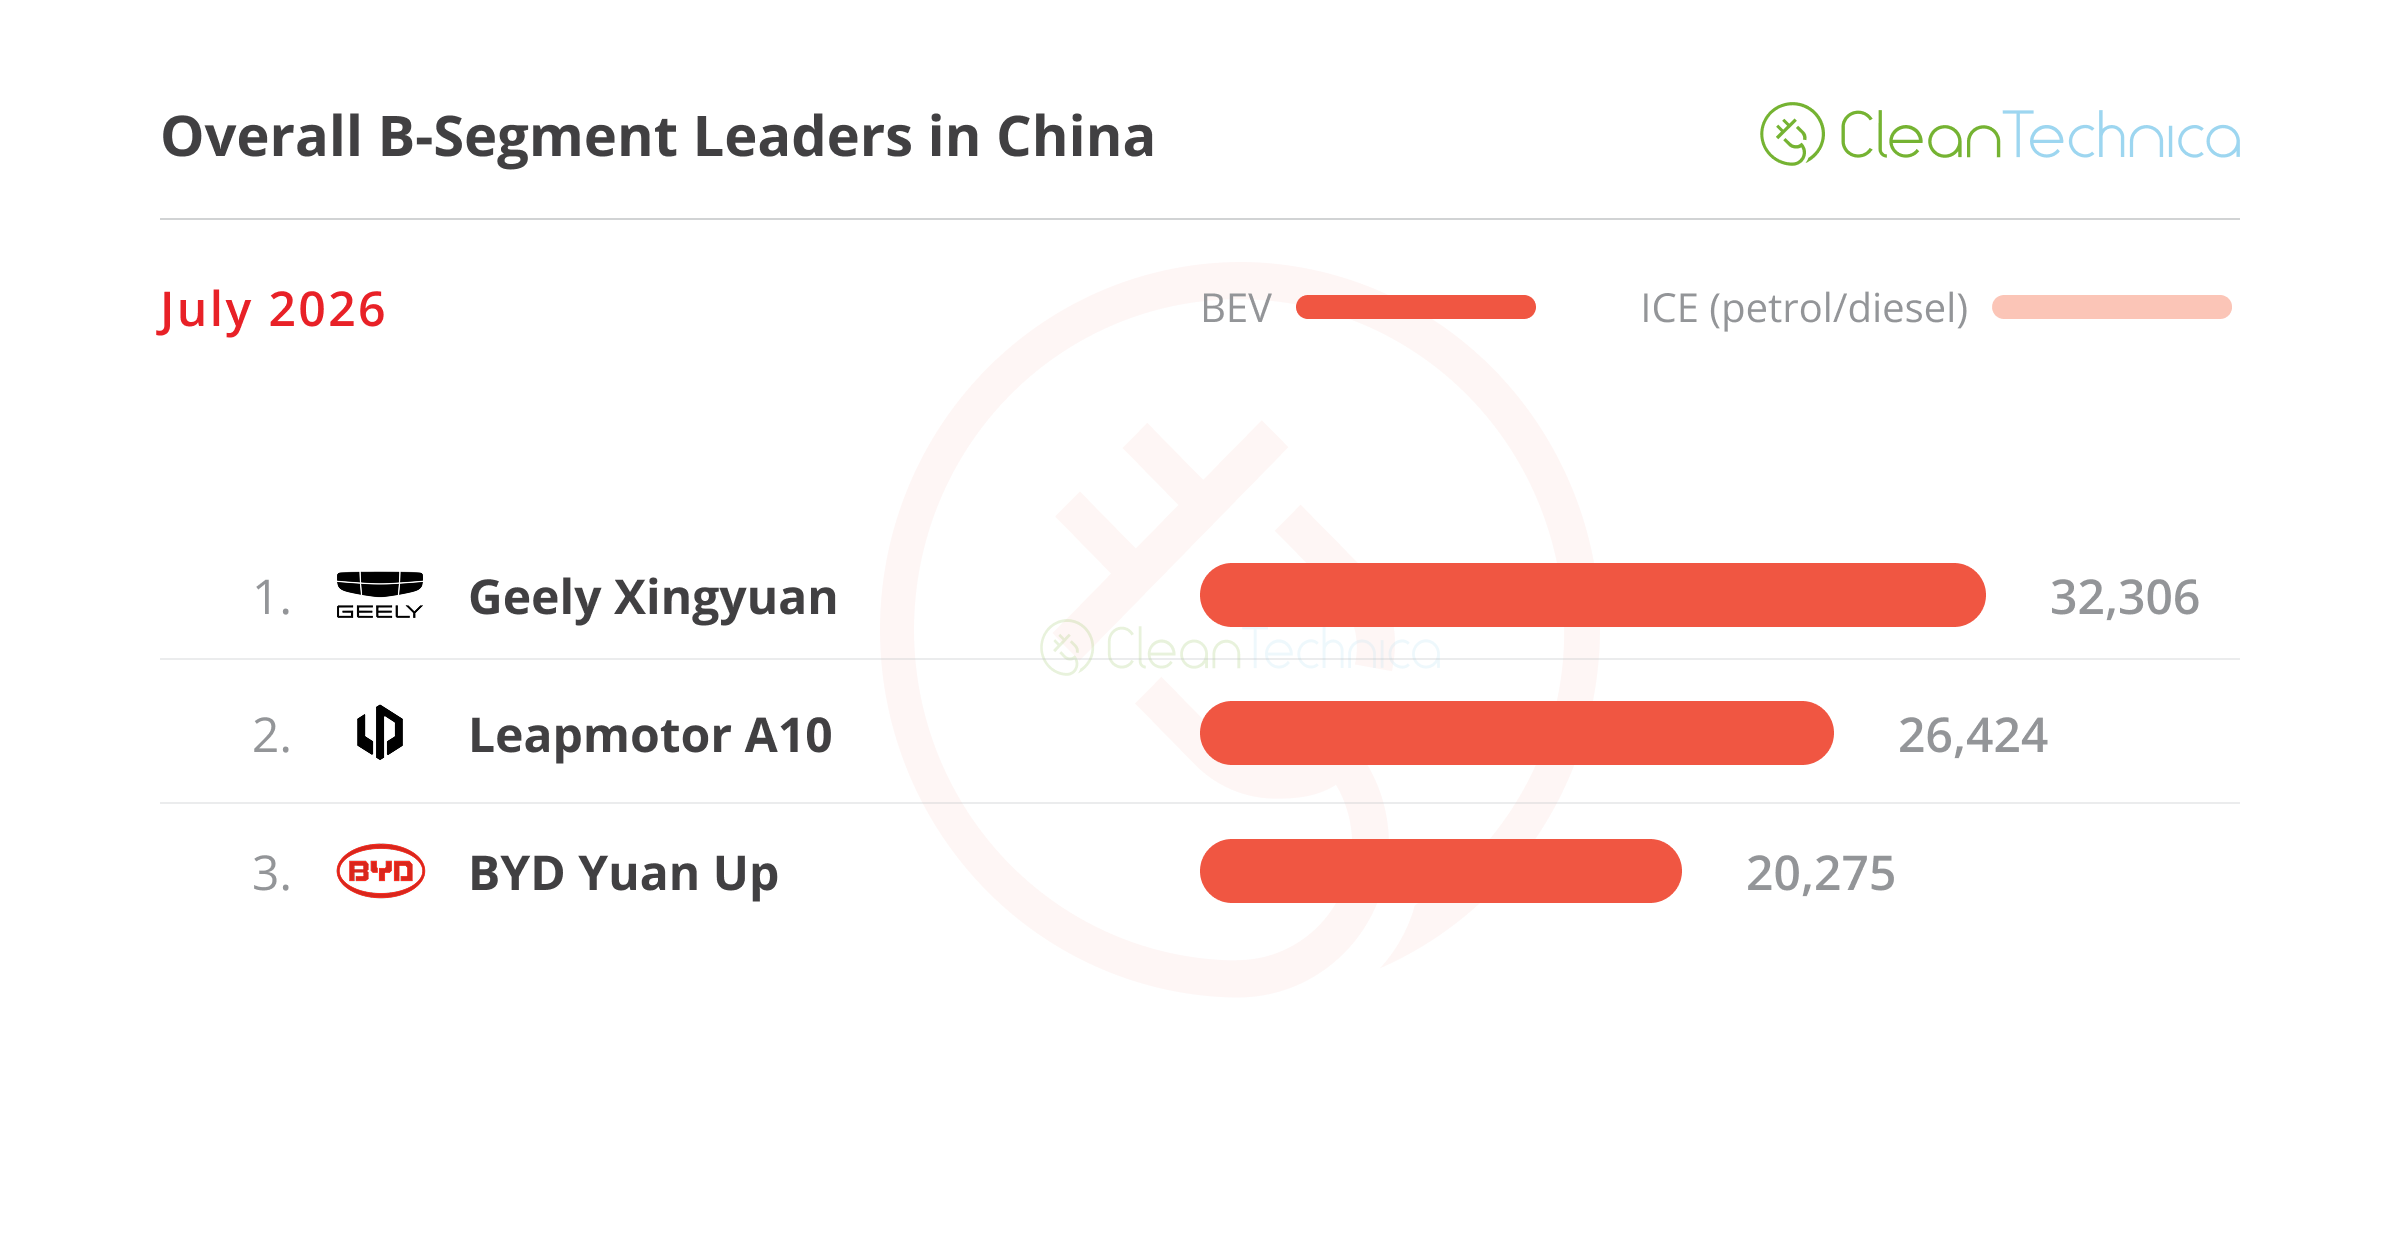
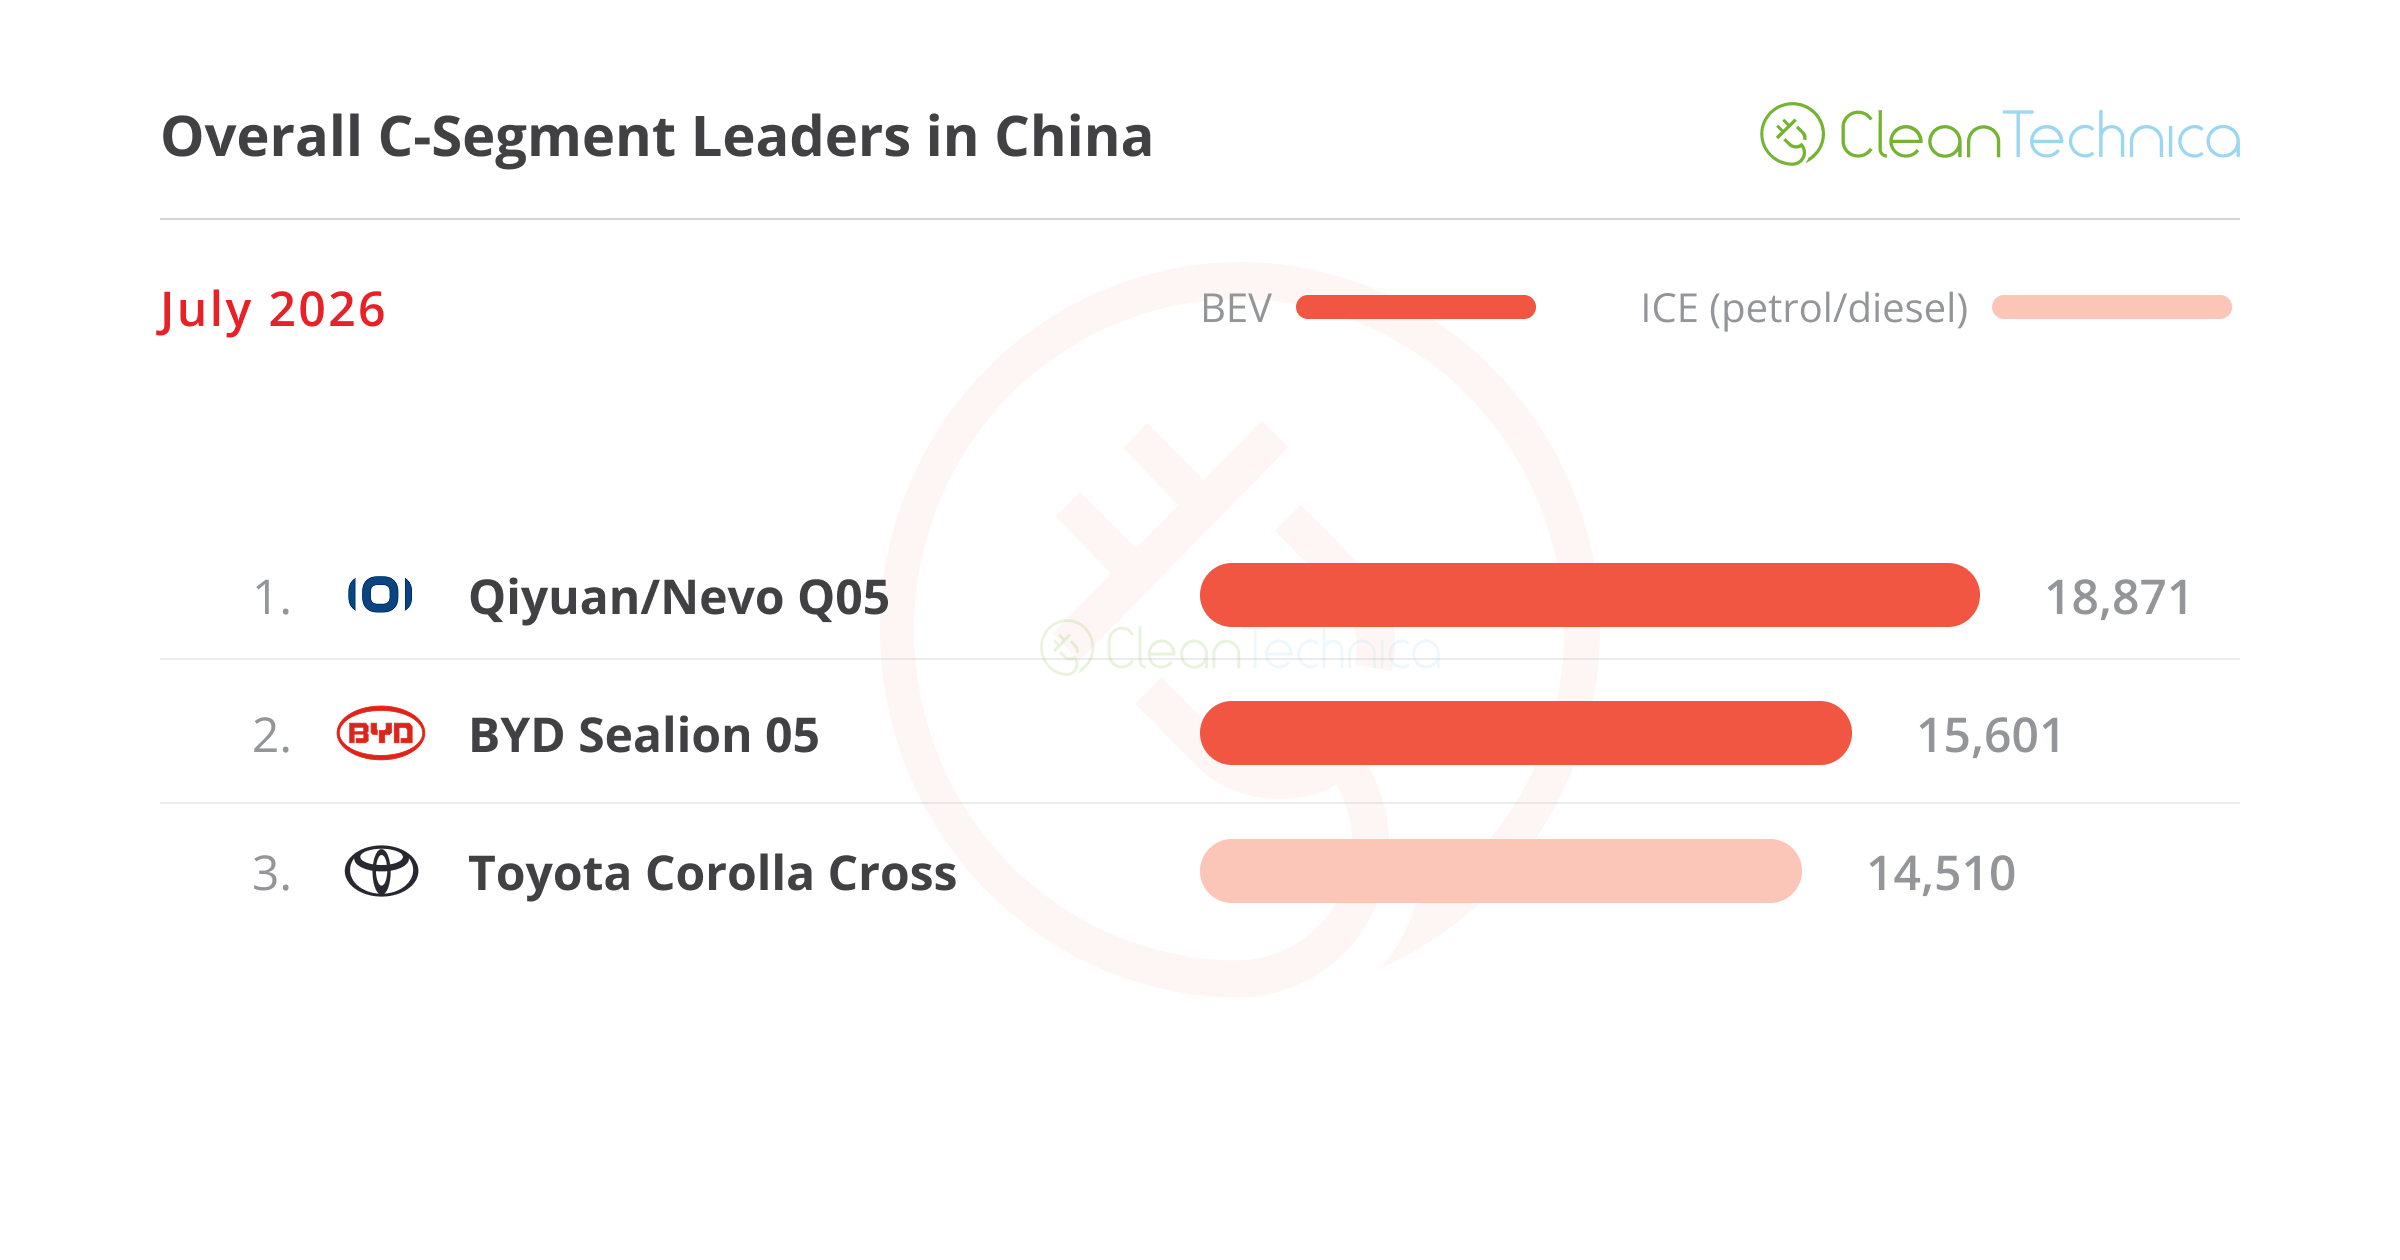

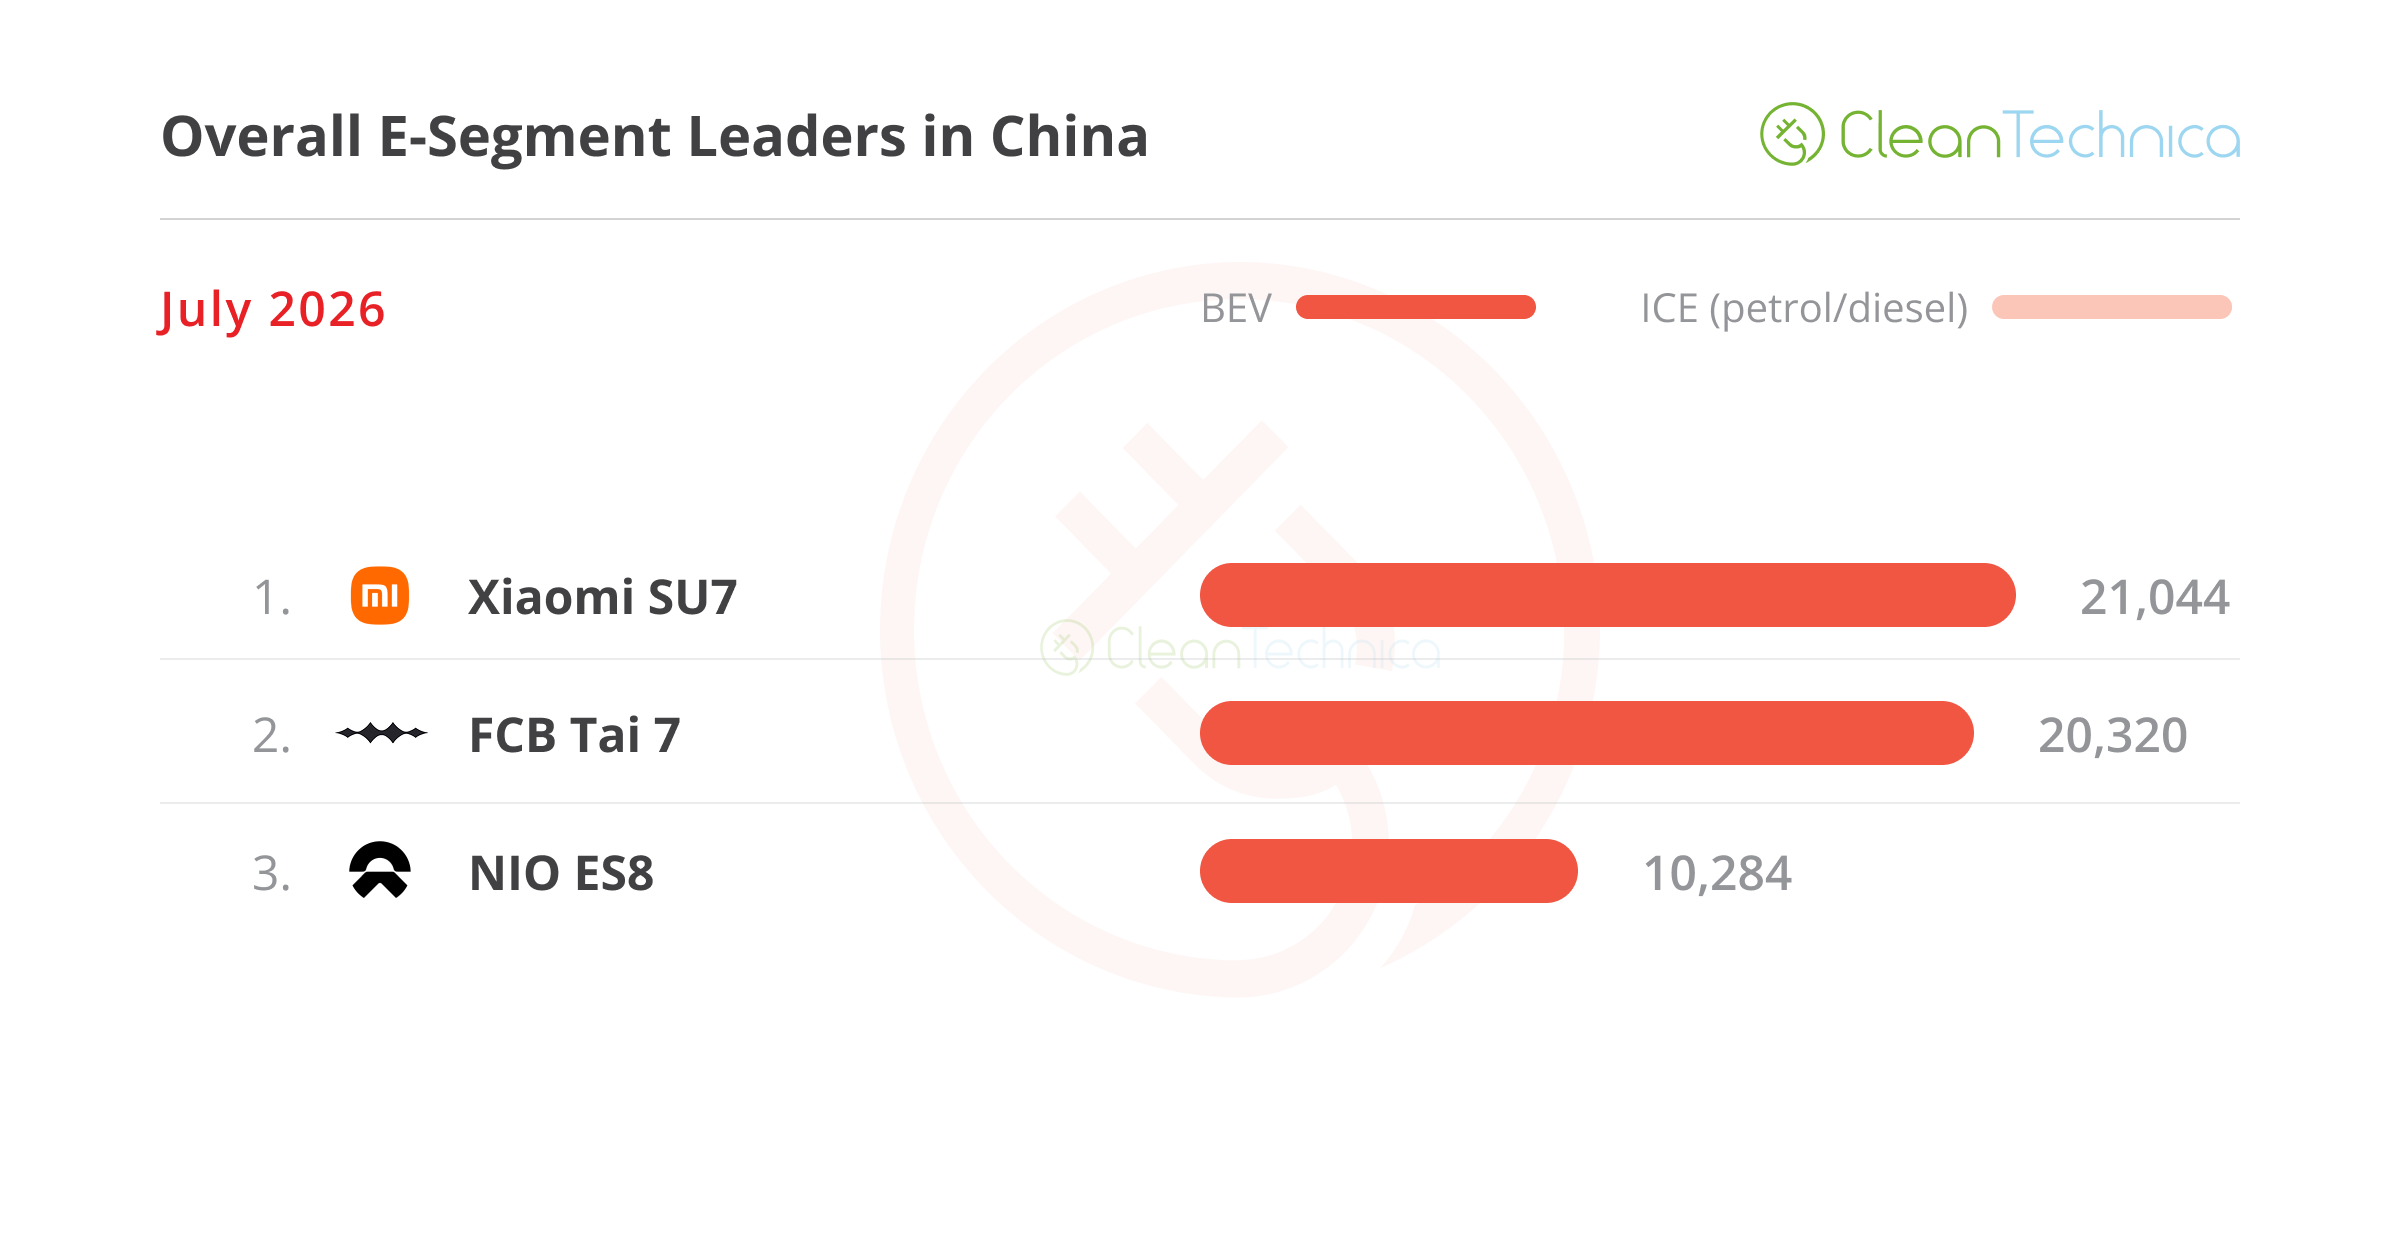
one of the best sellers in a number of measurement classes, EV disruption can also be fairly seen. Aside from the C-segment, all different measurement classes had 100% plugin podiums, and of those, solely 4 fashions weren’t 100% BEV.
Having a fast have a look at the 5 measurement classes, the spotlight is the shock management of the Qiyuan/Nevo Q05 crossover within the compact class, with the opposite shock being the one ICE consultant belonging to Toyota, on this case the Corolla Cross, ending July in third.
Model loyalty nonetheless counts, doesn’t it, Toyota?
The query is — for a way lengthy? I imagine it will likely be a matter of time till fashions just like the MG 4 or XPENG’s Mona EVs (the Mo3 and the upcoming L03) will be capable to take away that final of the ICE representatives from the compact podium.
Within the full measurement class, the NIO ES8 has managed to maintain the Xiaomi YU7 off of the rostrum, however with a rising Leapmotor D19 ending some 200 items behind the large NIO, we’d have a shock right here in August….
Additionally, two notes concerning the 2 smallest classes: The B section is having its greatest second ever as manufacturers attempt to replicate the Geely Xingyuan components. Nobody has thus far managed to get near it, however Leapmotor may be on the way in which there, as its new A10 crossover continues to ramp up manufacturing. And Leapmotor is just not completed but with the B section, because the A05 hatchback, a real Geely Xingyuan fighter, is ready to land quickly. And with a new-generation BYD Seagull additionally touchdown quickly, now aimed squarely at beating the Geely Xingyuan, the subcompact class is now the most popular factor within the Chinese language EV market.
As for metropolis vehicles, gross sales are affected by the subsidy reduce that got here originally of the 12 months, with the class slowly recovering from the dismal outcomes of the early months. Whereas the Wuling Mini EV remains to be the one related participant general, the Changan Lumin has reached 7,596 items in July, a brand new 12 months greatest, permitting it to win silver within the class, beating Bestune’s Xiaoma and Geely’s Panda. However what the class actually wanted was recent steel. BYD Racco, anybody?…

Right here’s extra information and commentary on July’s high promoting electrical fashions:
#1 — Geely Xingyuan
A BYD Dolphin for BYD Seagull cash ($10,000 USD). This was Geely’s inner memo to explain the components for the Geely Xingyuan when growing its star mannequin. With an fascinating title — Xingyuan interprets as “wishing upon a star” — evidently Geely had its want granted. The small hatchback has given the Hangzhou OEM the a lot coveted greatest promoting mannequin trophy. In July, the Geely mannequin received one other greatest vendor trophy, because of 32,306 registrations, which nonetheless represented a 27% drop over July 2025. Proof that competitors by no means sleeps in China, Geely’s hatchback is now having to take care of Leapmotor’s B-segment contenders, the A10 and A05, the new-generation Wuling Bingo, Chery’s new QQ3, let’s not neglect concerning the BYD’s Yuan Up, and, above all, the new-generation BYD Seagull, which has only one aim — to steal the Xingyuan’s crown.
#2 — BYD Tune (BEV+PHEV)
BYD’s midsize SUV is in a transition stage, and you may inform. Due to the ramp-up of the brand new Extremely physique, BYD’s star participant was 2nd, scoring 27,712 registrations. It thus narrowed the YoY gross sales drop to simply 7%. As soon as the brand new era is totally ramped up, the Tune will as soon as once more be a fierce adversary for the competitors to beat. The brand new Extremely era options lidar and 1,500 kW DC charging, and these two options aren’t even probably the most spectacular elements of the mannequin! That may be the worth. It begins at 152,000 yuan (or $22,000) with the 76 kWh battery, and it goes as much as 180,000 yuan (or $26,000) for the 83 kWh model. For comparability, the Tesla Mannequin Y begins in China at 259,000 yuan ($38,250)…. Anticipate the Tune to expertise a second youth within the second half of the 12 months, and whereas it needs to be laborious to displace the Tesla Mannequin Y from the second place place, the final place on the rostrum needs to be doable this 12 months. And possibly gold in 2027?
#3 — Leapmotor A10
Issues proceed to go properly for the startup model, with its new child A10 promising to be the star participant of an already sturdy lineup. Due to 26,424 registrations, the small crossover continues to ramp up manufacturing, successful its first podium end on the way in which. The mannequin has the standard value-for-money focus of the model, and a low, low value of 66,000 yuan ($10,000). On high of that, nevertheless, the A10 gives one thing near a definite character, because the design eschews the white product normal design of Leapmotor for one thing extra private, largely because of the back and front lights and a floating roof impact. One wonders how excessive the crossover will sit on the desk as soon as it’s at cruising velocity. Podium materials?
#4 — Tesla Mannequin Y
The prolonged wheelbase model, imaginatively referred to as “L,” helps the Mannequin Y’s fortunes in China. Nonetheless, in July, deliveries reached 25,158 items, a 18% drop over July 2025. The lengthy wheelbase model is proving to be of massive assist for the US crossover, preserving the Mannequin Y’s gross sales afloat, however new variants can solely achieve this a lot. When most direct opponents are transitioning into 800V platforms and including new options, the six-year outdated Mannequin Y is beginning to look a bit outdated. Nonetheless, the Tesla crossover has sufficient demand to supply it a podium place this 12 months. Subsequent 12 months, although? Arduous to see it getting there.
#5 — Xiaomi SU7
The King of Sedans. Issues proceed to go properly for the sporty mannequin, with the startup EV mannequin securing one other high 5 presence because of 21,044 registrations. With a excessive quantity of tech, nice consolation, and a sporty ethos to go together with it, the SU7 success reveals that there’s nonetheless life within the sedan class. You simply have to make them interesting.… In any case, in a world full of boring crossovers and SUVs, sedans might be what coupés and sports activities vehicles have been a number of many years in the past — sexier automobile decisions for people who discover extra family-friendly fashions simply too drab and uninteresting.

the remainder of one of the best vendor desk, the spotlight within the high half was the Fang Cheng Bao Tai 7, which had its greatest consequence this 12 months thanks to twenty,320 registrations, all whereas the Li Auto i6 had a sluggish month dropping to #10, with 15,420 registrations.
As for the second half of the desk, issues have been extra fascinating. GAC’s Aion i60 reached the desk, because of 11,186 registrations, a brand new document for the compact crossover. Nonetheless in document territory, the brand new Chery QQ3 EV debuted within the high 20, in seventeenth, with a document 10,780 registrations. Chery has excessive hopes for its new child, because the Wuhu make hopes it could actually replicate the Geely Xinguyan’s success with its personal small hatchback.
A ultimate word on the BYD Seal 06, #19 in July: not for its gross sales efficiency in itself — in any case, 10,390 deliveries is just not significantly a powerful month for the midsizer — however as a result of over 1,500 of the items belonged to the station wagon physique, a not insignificant proportion of its gross sales and extra proof that station wagons are beginning to be “a factor” in China, a market that till lately was marginal at greatest. With different station wagons additionally experiencing reasonable success (NIO ET5, Zeekr 7 GT…), one can hope that station wagons will profit sooner or later from fatigue with the present SUV/crossover craze and as extra fashions turn into obtainable.
Exterior the highest 20, a number of fashions deserve a point out.
Beginning within the land yacht class, each Leapmotor and Xpeng had their takes on the subject, ramping up manufacturing and reaching related volumes. Leapmotor’s D19 scored its first five-digit consequence (10,043 registrations), that means {that a} high 20 presence needs to be doable quickly, whereas Xpeng’s Vary Rover GX had 7,016 items delivered.
Additional down the meals chain, the BYD Yuan Plus had its greatest month since final September, 9,246 registrations, all because of a brand new era of the compact crossover that ought to assist it claw again into the highest 20.
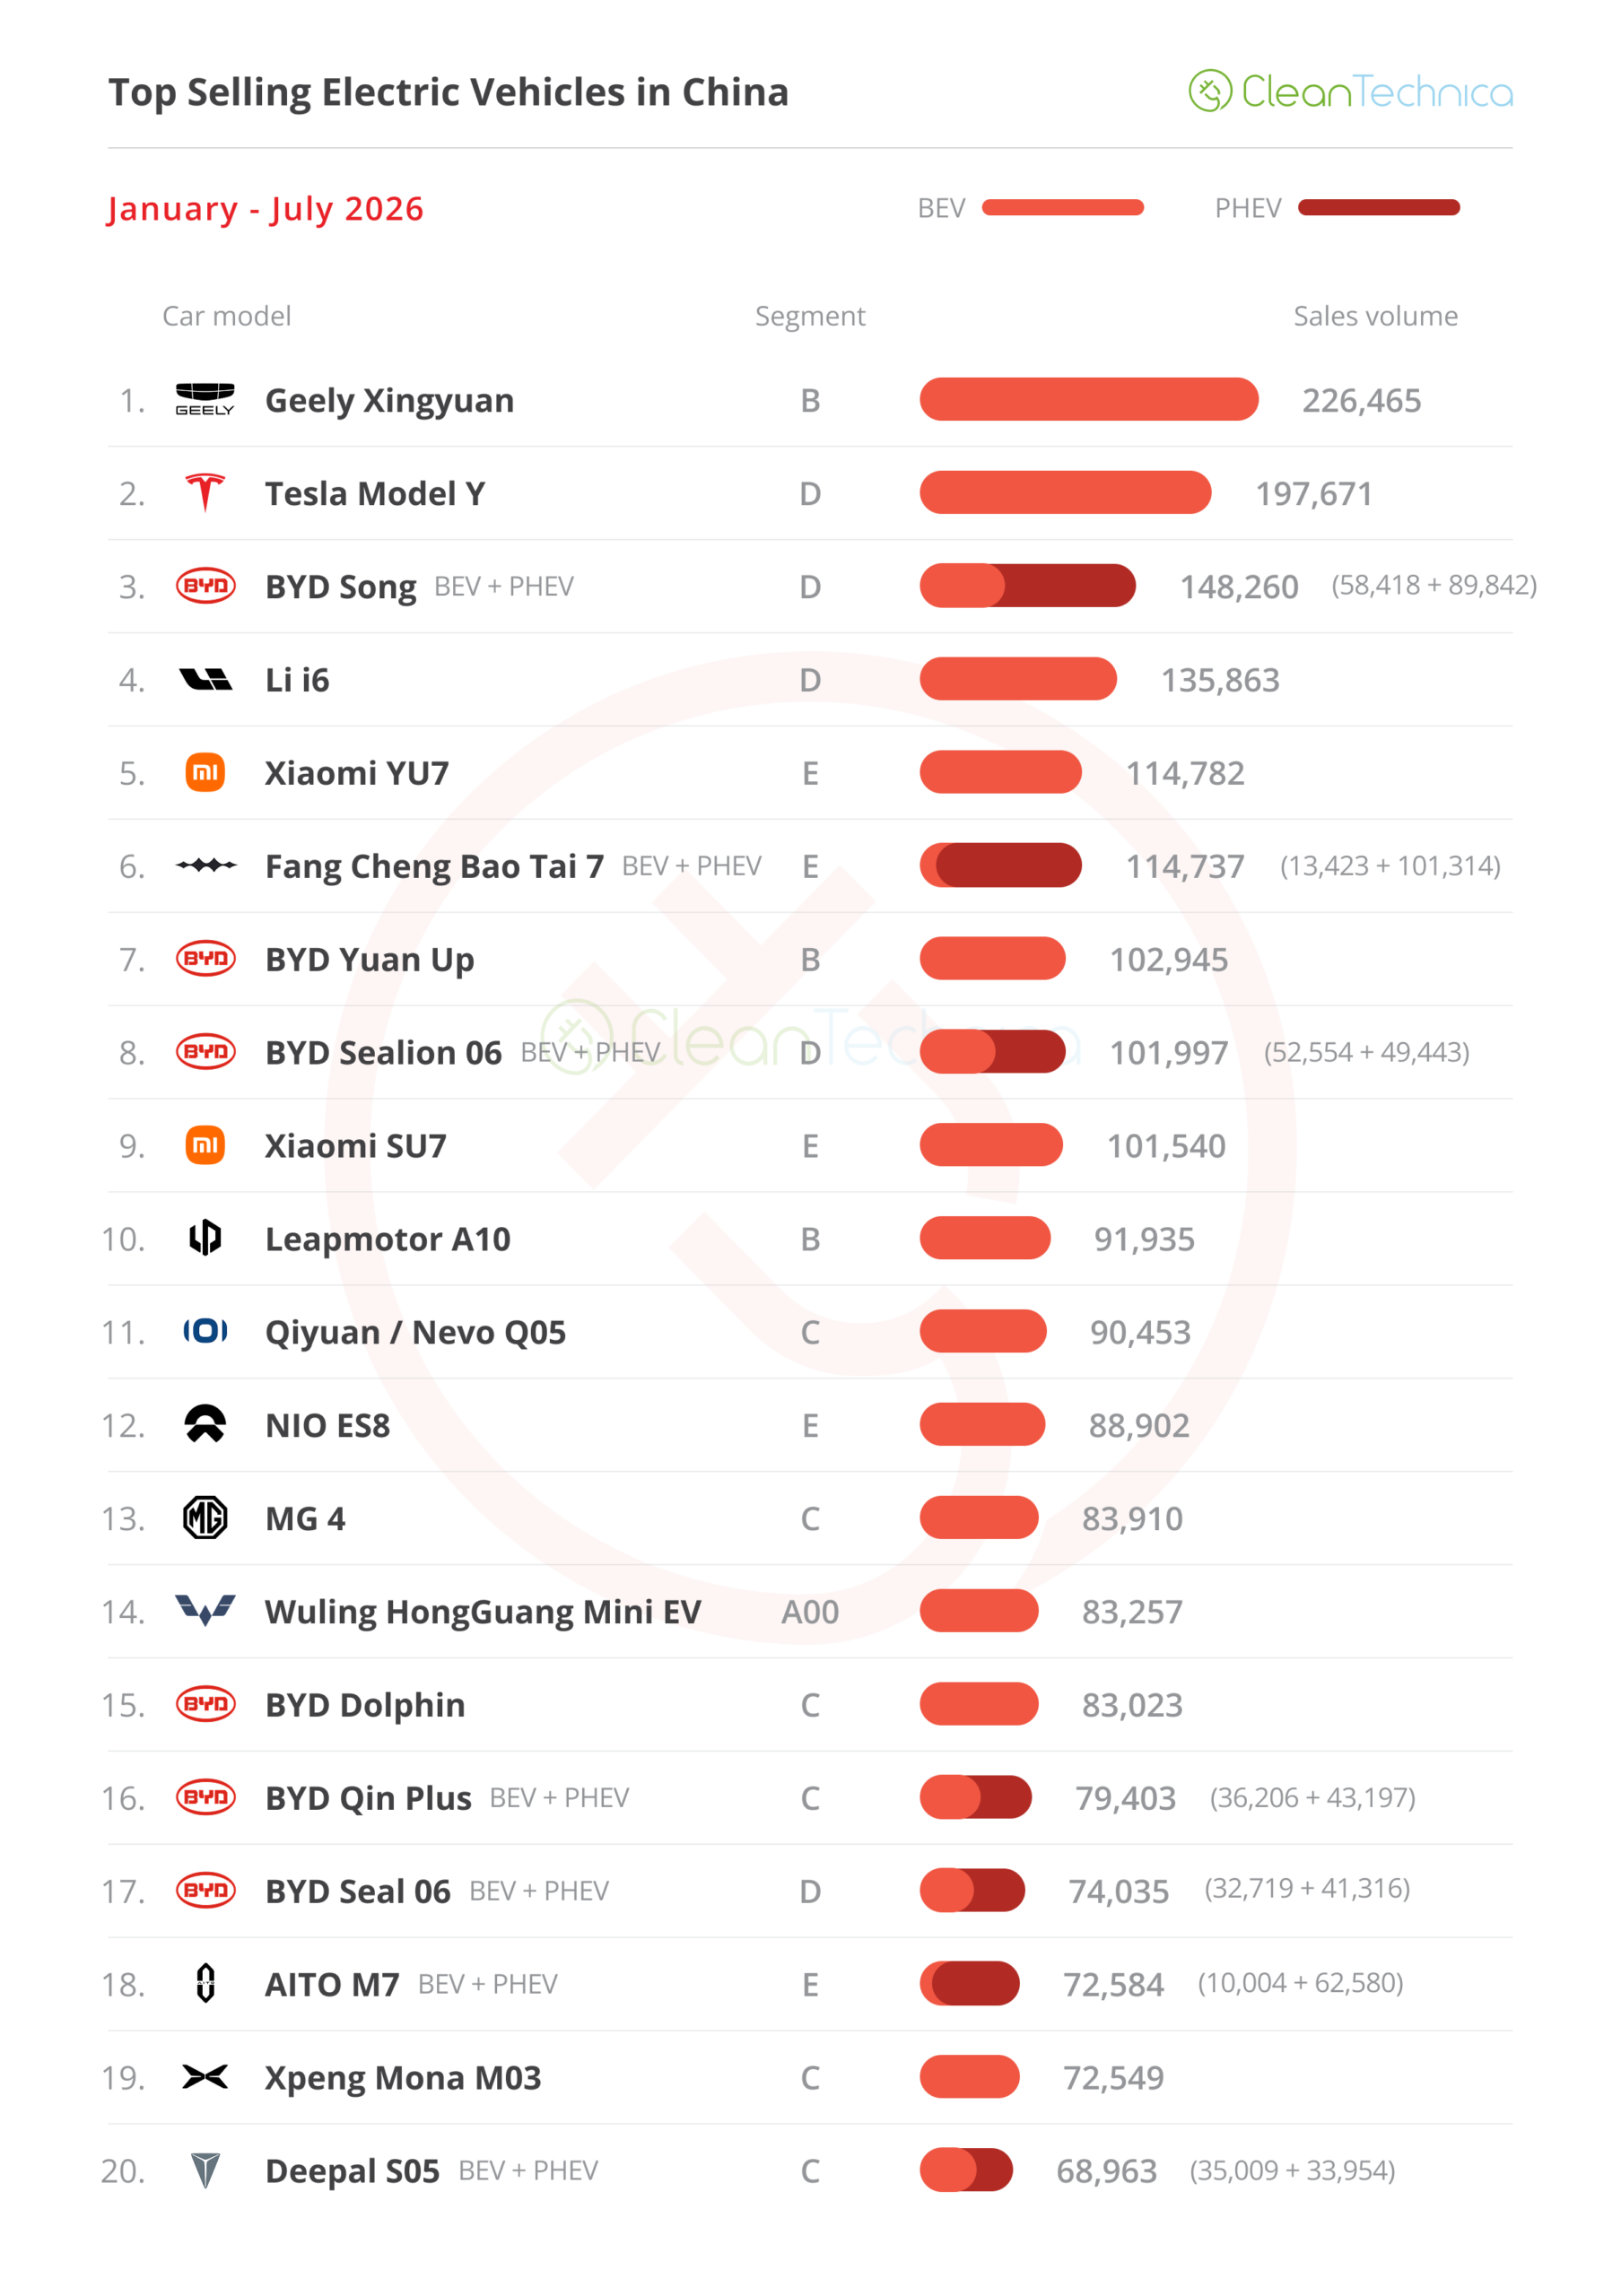
Trying on the 2026 rating, the rostrum remained the identical, and until one thing surprising occurs, it ought to keep as it’s till the tip of the 12 months, with the small Geely repeating its 2025 win, the Mannequin Y returning to silver after its bronze in 2025, and the BYD Tune getting again onto the rostrum after a one-year absence.
Under the rostrum positions, BYD had two fashions on the rise. The BYD Yuan Up went as much as seventh, whereas within the second half of the desk, the BYD Seal 06 profited from a dismal month for the AITO M7 (solely 4,500 items) to climb one place into seventeenth.

However the main information lie elsewhere. The Climber of the Month was the lately launched Leapmotor A10, which jumped 9 spots from nineteenth in June to its present tenth place. With the small crossover nonetheless ramping up, I wouldn’t be shocked to see it attain the seventh spot quickly.
Changan additionally had a very good month, seeing its mainstream Qiyuan Q05 climb one place into eleventh, all whereas its extra premium cousin, the Deepal S05, joined the desk in twentieth.
“Hey, I’m not seeing the Tesla Mannequin 3 on the desk!” And your eyes haven’t deceived you. The US sedan is just not within the high 20, as a result of in July it dropped to twenty first, some 400 items under the #20 Deepal S05. Positive, it will likely be again on the desk, if not in August, then absolutely in September, making the most of its normal end-of-quarter peak. However….
That is the Mannequin 3’s new actuality. After successful the Greatest Promoting EV title in China again in 2020, the one international mannequin ever to realize that, and successful the third spot within the following 12 months, it has been a sluggish, however regular, decline for the midsizer. Its ambition now could be restricted to easily staying within the high 20.
This July it delivered solely 2,091 items, a 78%(!) YoY drop, and whereas there are a number of explanations for this drop, the Mannequin Y, at present 2nd within the desk, is just not having the identical form of gross sales crash. So, in addition to being an older mannequin, it additionally sits in a class, sedans, that has usually been affected by the crossover/SUV fever. There are 12 crossover/SUVs within the high 20, towards 4 hatchbacks and 4 sedans.
Nonetheless, it’s when evaluating these sedans towards the Tesla Mannequin 3 that one realizes the actual purpose why the US mannequin is falling behind:
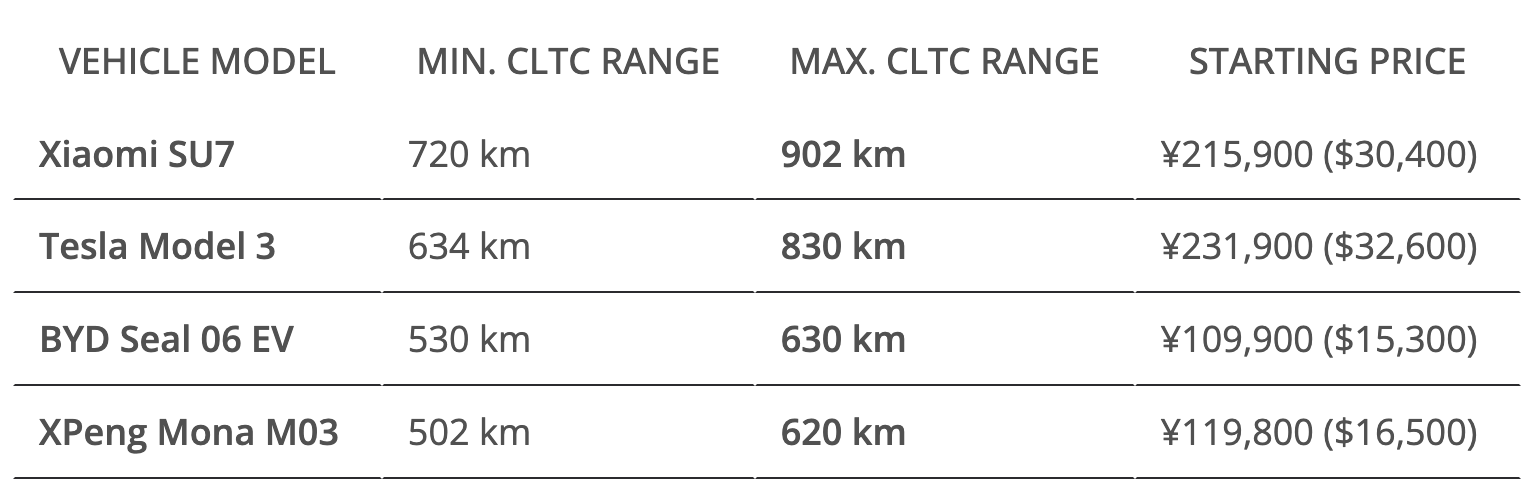
Tesla can’t compete on value, as their opponents are promoting at half value, however it could actually now not compete on worth both, because the Xiaomi sedan is a greater (and dare I say, sexier) proposal for roughly the identical value.
Trying on the general producer rating, it’s a sea of crimson. Everyone seems to be dropping gross sales — large time. Toyota’s 17% drop may very well be thought-about a win once we have a look at the 32% drop of BYD, the 27% drop of Geely, and the 41%(!) crash of the as soon as almighty Volkswagen, now solely in 4th.
So, if the large boys on high are crashing, who’s successful?
Reply: Startups. And particularly Leapmotor. The Hangzhou startup was up an astonishing 84% YoY, to 83,698 registrations, ending the month fewer than 4,000 items under Volkswagen….
And with loads of recent steel coming in (A10 and D19 ramping up, new A05, D99…), anticipate gross sales to proceed on the way in which up, endangering the positions of not solely VW and Toyota as they attempt to adapt to the brand new realities of the market, however even large shot Geely might turn into threatened by Leapmotor.
I imply, it simply takes LP’s A10 and A05 beginning to steal related gross sales from the Geely Xingyuan and Geely might begin seeing its silver medal slip from its arms, and into Leapmotor’s….
Trying under the highest 10, a number of extra manufacturers are experiencing surging gross sales, like #16 Zeekr. Geely’s premium arm jumped 75% YoY to 26,000 items offered. At #12, we now have one other premium model, this time BYD’s Fang Cheng Bao, which is surging 109% YoY to 29,000 items. In the meantime, Qiyuan/Nevo is at #14, with 28,000 items offered, a 108% quantity enhance in comparison with the identical interval in 2025.
Alternatively, there are many international makes in deep crimson, with probably the most shocking of them being Honda, solely 18th in July, having seen its gross sales crater by 44% YoY in July to 25,000 items, 1 / 4 of what arch-rival Toyota had in the identical month.
After which there may be Common Motors. After confirming that Chevrolet is leaving China, Buick can also be in a foul place, having seen its gross sales drop by 37% YoY in July, to some 23,000 items.
However many extra are additionally on the way in which out. In July, Ford offered solely 3,800 items, down 61% YoY. In the identical interval, Lincoln offered 1,500 items, down 49% YoY, whereas each Peugeot and Citroen offered fewer than 1,000 items, round half of what they offered a 12 months in the past.
Lengthy story brief, the Chinese language automotive market is at present a story of two totally different markets — a shrinking outdated ICE one, the place international legacy OEMs nonetheless maintain the bulk, and the more and more extra vital EV market, the place native manufacturers dominate the panorama.
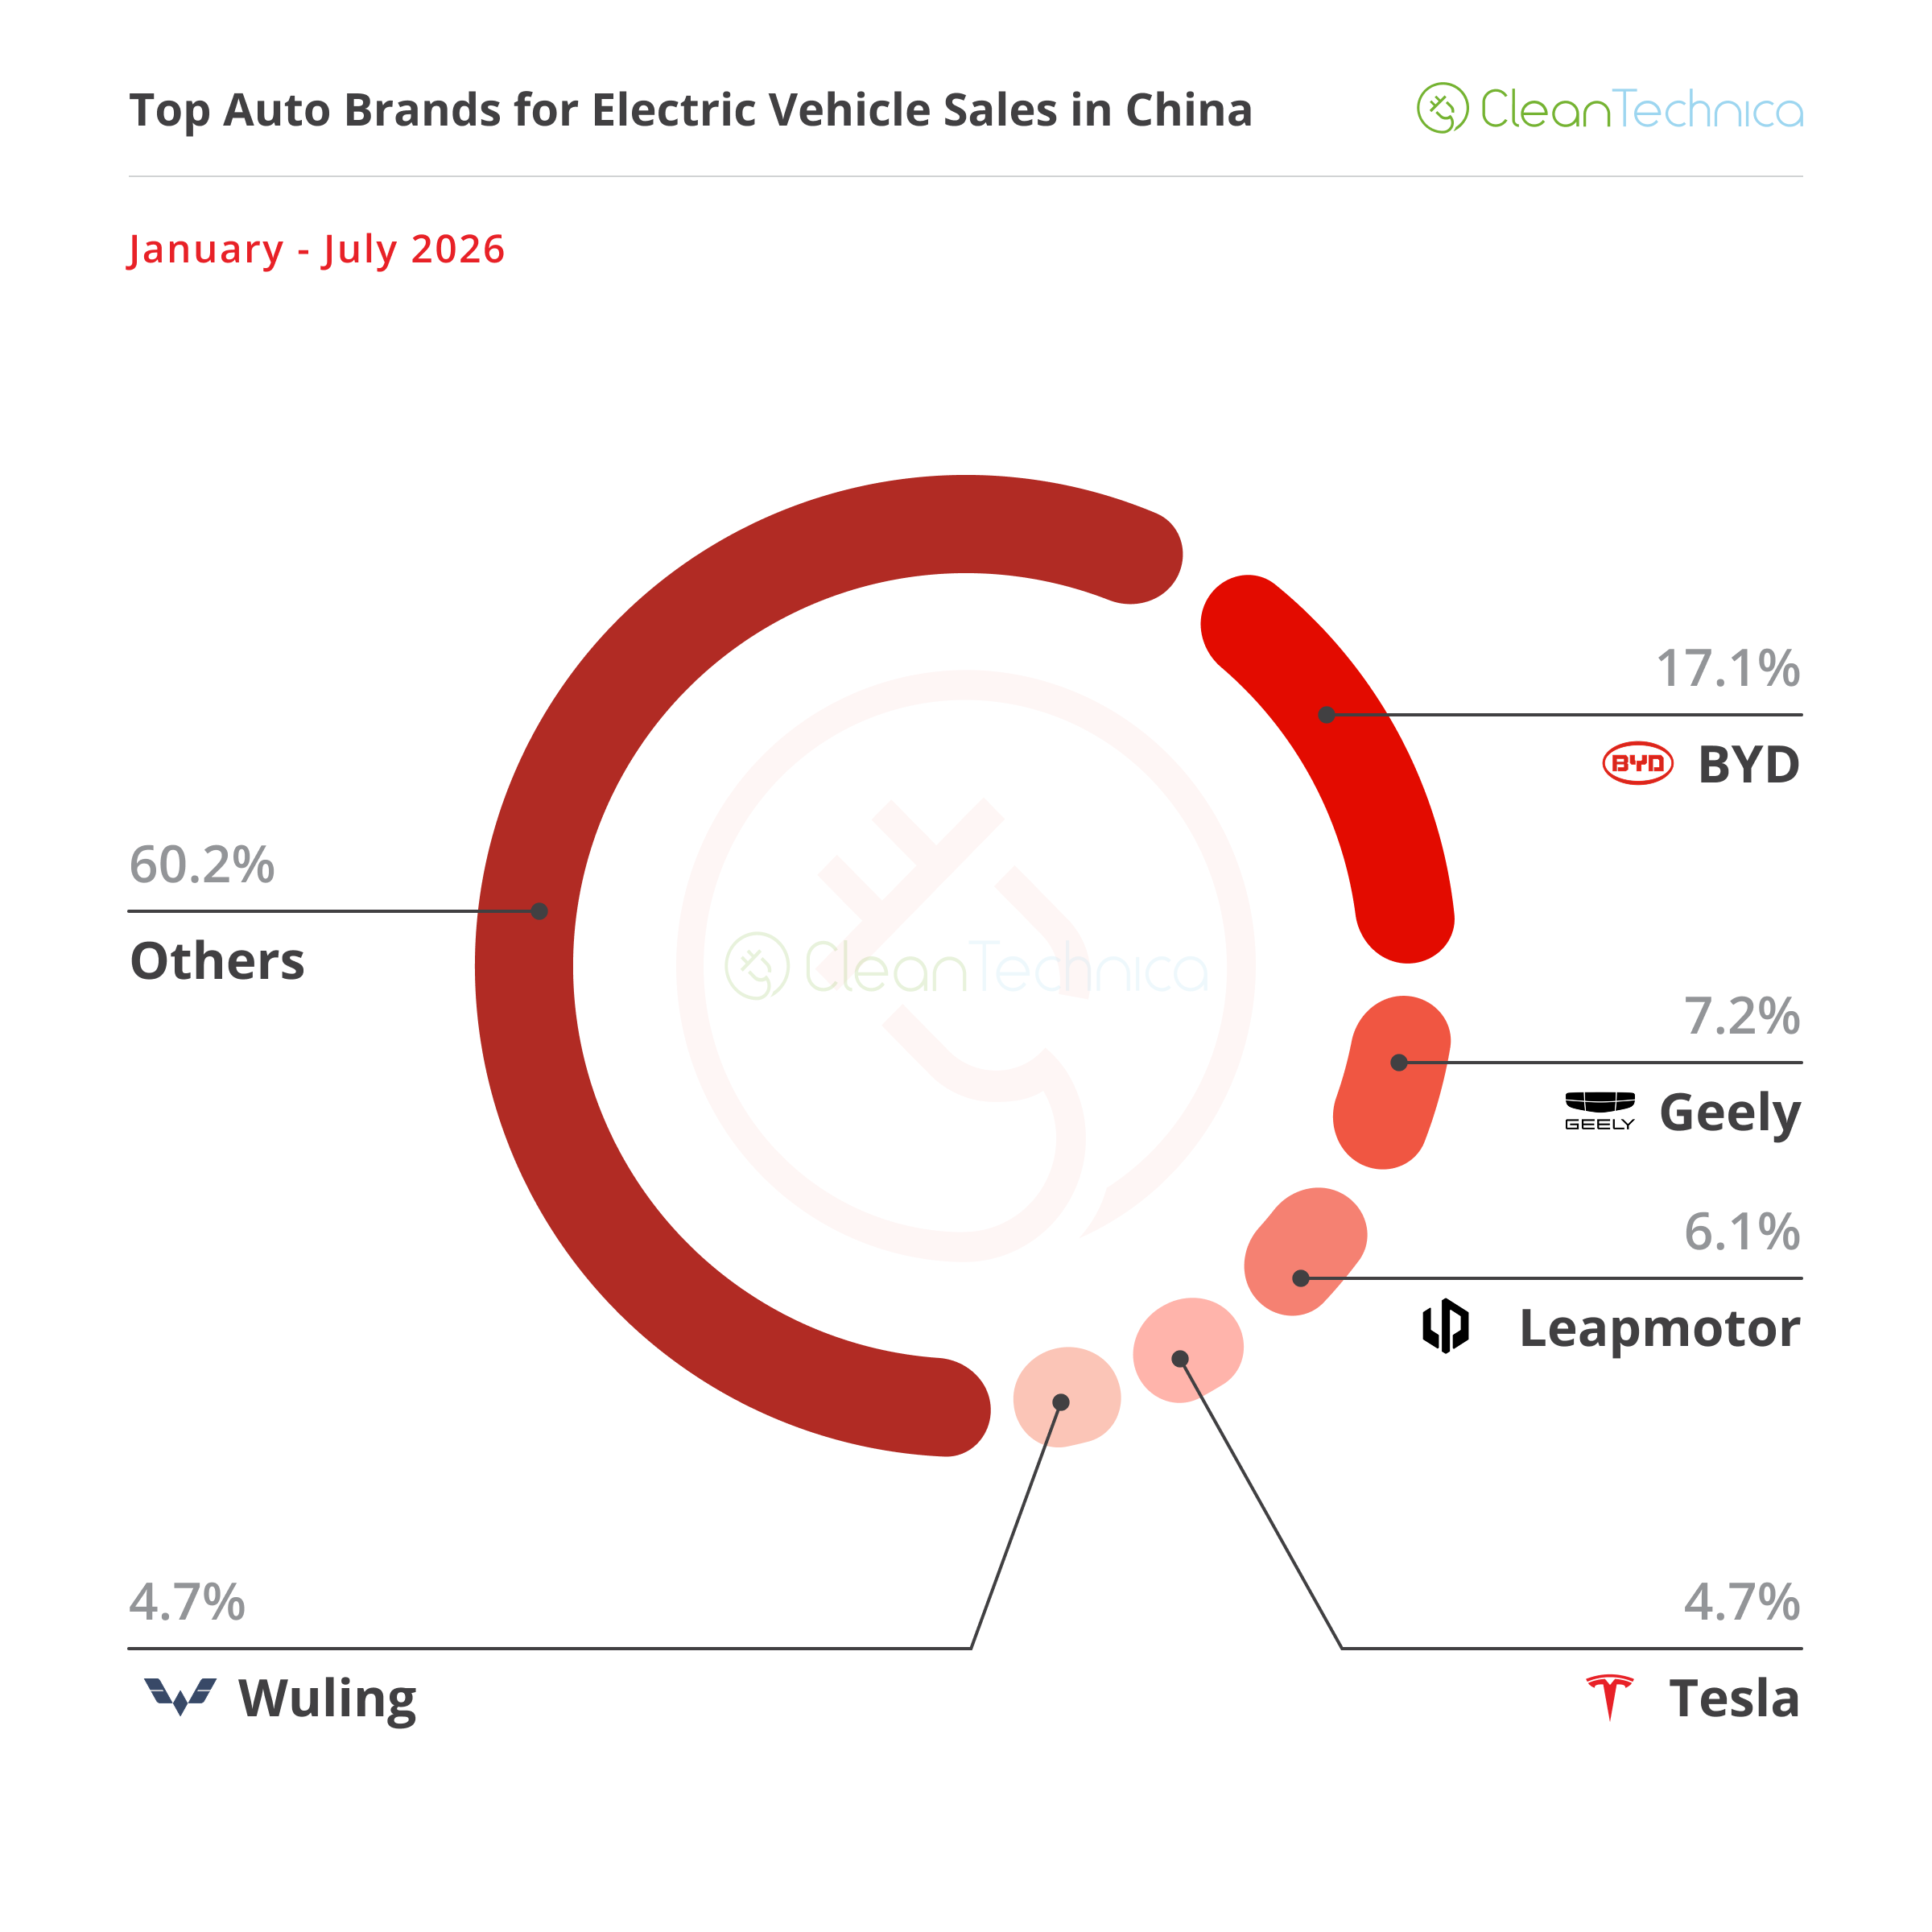
Trying on the auto model rating, there’s loads of information. Chief BYD is agency within the management spot (17.1%), whereas runner-up Geely continues to slip (7.2%, down from 7.4%).
Which means rising Leapmotor (6.1%, up 0.6%) is now lower than 1% behind Geely, so it received’t be shocking if in a few months, we noticed the startup model turn into the brand new silver medalist.
In the meantime, Tesla (4.7%, down 0.4%) barely held on to the 4th spot, with #5 Wuling (4.7%) trying menacingly within the rearview mirror. Nonetheless, anticipate Tesla to maintain the #4 place, because the September peak ought to assist it acquire distance over Wuling.
#6 Li Auto (4.1%) and #7 Xiaomi are nonetheless a methods off from SAIC’s make, so the highest 5 ought to stay as it’s within the following months.

OEMs/automotive teams/alliances, BYD is main, with 21.4% share of the market, up 0.3% in July. The chief is benefitting from the continued success of Fang Cheng Bao, and from a powerful month popping out of Denza.
In the meantime, #2 Geely misplaced 0.2% share and acquired right down to 12.1%, however the multinational conglomerate nonetheless had the runner-up spot secured.
#3 SAIC was down (8.1%) as a result of Wuling’s sluggish month, however remained agency within the final place on the rostrum, whereas #4 Changan can also be secure in 4th (6.7%, down 0.1%).
Having stated that, the fifth positioned Leapmotor (6.1%, up 0.6%) might turn into a risk quickly to #4 Changan, and possibly even to #3 SAIC later within the 12 months.
Leapmotor is turning into critical enterprise, because of a targeted lineup that’s on the identical time broad, masking every part from metropolis vehicles to full measurement ones however with out going into the lineup byzantine follies of BYD, the place you will have a number of fashions for only one class (instance: midsize sedan BEV class: BYD e7, Qin L EV, Seal 06 EV, Seal).
At this tempo, I wouldn’t be shocked if in a number of years (2030?), Leapmotor turned a bigger automaker than Tesla … globally.
Join CleanTechnica’s Weekly Substack for Zach and Scott’s in-depth analyses and excessive degree summaries, join our day by day e-newsletter, and observe us on Google Information!
Have a tip for CleanTechnica? Need to promote? Need to counsel a visitor for our CleanTech Speak podcast? Contact us right here.
Join our day by day e-newsletter for 15 new cleantech tales a day. Or join our weekly one on high tales of the week if day by day is simply too frequent.
CleanTechnica makes use of affiliate hyperlinks. See our coverage right here.
CleanTechnica’s Remark Coverage
